

Rate: Home, Finance & Wellness
Guaranteed Rate, Inc
- 4.7
- 82.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
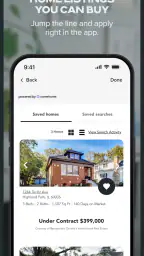
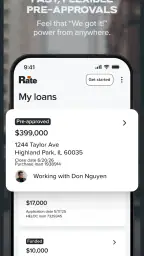
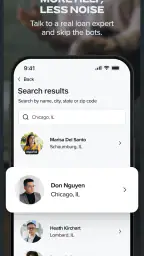
Rate: Home, Finance & Wellness Pros and Cons
Pros
- User-friendly interface, easy to navigate.
- Comprehensive finance tracking tools.
- Customizable wellness goals.
- Syncs with smart home devices.
- Regular updates with new features.
Cons
- Limited free version features.
- Occasional sync issues reported.
- High battery consumption.
- Requires constant internet connection.
- Some features behind paywall.
 Analysis by All-app
When money and home responsibilities are shared, a finance app can help only if everyone is clear about whose information is being entered and who is expected to act on it. I see Rate: Home, Finance & Wellness as a possible starting point for bringing those conversations together, rather than a replacement for a bank account, a household agreement, or a proper discussion about privacy. That distinction matters: an app can make routines easier to see, but it cannot decide what a family should share.
A practical place for household routines
Picture a couple planning the month at the kitchen table. One person handles utility bills, the other keeps an eye on groceries, and both want to make room for a savings goal. A shared review of the budget and home tasks can make that conversation more concrete: instead of relying on memory, they can talk through spending, upcoming responsibilities, and what needs attention. The useful part is not simply recording activity; it is giving the household a reason to check in before a small oversight becomes a stressful surprise.
I would use it as a prompt for a brief weekly or monthly conversation, not as a live scoreboard of who spent what. For example, a household could agree to review the budget together on a chosen day, then decide who will follow up on a bill or maintenance task. That routine can work even when only one person enters information, provided everyone understands that the record is not necessarily a complete shared account of every transaction.
That distinction is especially important for roommates. They may share rent, utilities, or repairs without wanting to combine personal finances. In that situation, the app’s broad mix of finance and home themes may help organize a conversation, but I would keep any personal figures private unless everyone has agreed on what belongs in a shared view. A simple split-payment arrangement or a dedicated expense-sharing tool may be a better fit if the only problem is dividing common costs.
Set boundaries before entering household details
Before using any finance app around other people, I recommend deciding what you want it to represent. Is it a personal budget that you sometimes discuss, or a household plan that everyone contributes to? Those are different arrangements. Start with a small, low-risk routine—perhaps tracking a shared household category or listing a maintenance reminder—then see whether the workflow suits the people involved before adding more detail.
It is also worth agreeing on who will maintain the information. If one person enters expenses and another assumes the records are complete, the resulting picture can be misleading. A household budget is only as useful as its entries and the agreement behind them. I would label responsibilities clearly in conversation, verify important figures against the original bill or account, and avoid treating an app’s summary as proof that everyone has recorded every purchase.
For account boundaries, each adult should make an informed choice about using their own device and account rather than casually passing around a logged-in phone. A shared screen can expose more than the person holding it intends to show, especially when financial information is involved. If you are setting up the app for someone else, let that person review the choices and enter their own sensitive details where appropriate. Convenience should not quietly become access without consent.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
There is another practical trade-off: a household can create extra work if it tracks the same information in several places. If you already rely on a bank app for transactions, a spreadsheet for bills, and a calendar for repairs, decide which source is authoritative for each item. Using this app as a planning space while leaving account balances in the bank’s own app may be more sensible than trying to duplicate everything. The goal is fewer missed handoffs, not a second bookkeeping job.
Coordination without assuming everyone shares everything
The combination of money, wellness, and home management suggests a broader way to think about household pressure: finances are connected to routines, maintenance, and personal wellbeing. Still, I would not assume that every member needs access to every part of that picture. One adult may want help keeping bills and goals in view, while another prefers to discuss only the shared expenses. Good coordination can mean agreeing on a summary, not opening every personal detail.
A useful workflow is to decide what needs attention first, then use the app to support that decision. If a bill is due soon, the household can confirm who will handle it and where the payment will be made. If a repair is needed, someone can take responsibility for arranging it and check that the task is completed. The app can help keep the topic visible, but the actual payment, booking, or agreement still needs a person to follow through.
For a family with changing schedules, a short check-in may be more effective than expecting everyone to monitor an app throughout the day. I would avoid interpreting a reminder as a complete coordination system: reminders help only when the right person sees them and understands what action is expected. If a task is urgent or affects safety, direct communication is the better channel.
Compared with a basic spreadsheet, an app can feel more approachable for someone who does not want to build categories or formulas from scratch. Compared with a bank’s own app, a broader home-and-wellness focus may encourage planning beyond account balances, while the bank remains the better place to confirm transactions and manage banking details. And compared with a specialist bill-splitting service, this app’s apparent appeal is its wider household context, not necessarily the most direct way to settle shared expenses. I would choose based on the task I need to solve, rather than expecting one tool to replace every other one.
Age, trust, and a sensible level of access
The app is rated for Everyone, but an age label is not a substitute for a family decision about financial privacy. A younger person might take part in a conversation about saving or household responsibilities without needing access to an adult’s personal financial information. I would keep those two things separate: teaching budgeting can be useful, while sharing private account details is a different choice that deserves care.
Trust also depends on the quality of the information. If an adult is using the app to plan shared bills, everyone affected should know whether the figures are estimates, manually entered amounts, or checked against actual statements. That small clarification prevents a tidy-looking screen from being mistaken for a complete or official record. I would especially verify due dates and amounts with the original bill before acting, since a planning tool should not be the only checkpoint for a consequential payment.
With an older relative or someone less comfortable with technology, I would offer help without taking control of their personal account. Sit together, explain what each entry is for, and let them decide what information they want to include. If they only need occasional help organizing home tasks, a shared calendar or written checklist may be clearer and less intrusive. The right tool is the one the person can use confidently and willingly.
Rate: Home, Finance & Wellness is a free finance app from Guaranteed Rate, Inc. It has a 4.7 average from around 880 ratings and has passed 100,000 installs. It was released in May 2023, and version 1.36-prod is listed for Android 6.0 and later. Those details make it easy to understand why it may attract people looking for a low-cost way to explore money and home organization, but popularity alone does not tell me whether its approach matches a particular household.
How the app feels in everyday use
I recently got my hands on the Rate: Home, Finance & Wellness app, and let me tell you, it’s like having a personal finance guru right in your pocket. Whether you're a budgeting newbie or a seasoned financial wizard, this app offers something for everyone. So, grab a coffee, sit back, and let me take you through my experience with this fantastic app.
First Impressions and User Interface
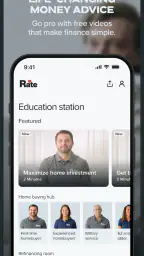
The moment I opened the app, I was greeted by a clean, modern interface that feels intuitive and user-friendly. The design is sleek, with soft colors and minimalistic icons that make navigation a breeze. You won’t find yourself lost here; everything is just a tap away. It’s clear that a lot of thought went into making sure users can easily find what they need without getting overwhelmed.
One of the first things I noticed was how smooth the transitions were between sections. The app doesn't lag, and everything loads quickly, which is a huge plus for someone as impatient as I am! From the home screen, you can access different features like budgeting tools, wellness tips, and home management features with just a couple of taps.
Features Galore
Now, onto the juicy part — the features. This app isn’t just about crunching numbers; it’s about creating a holistic approach to financial wellness. Here’s a quick rundown of what you can expect:
- Budgeting Tools: These tools are comprehensive and customizable. You can set your monthly budget, track your expenses, and even categorize your spending. It’s like having a digital envelope system, but way cooler.
- Financial Insights: The app provides insights into your spending habits, helping you identify areas where you can save. The visual charts are super helpful in breaking down complex data into understandable chunks.
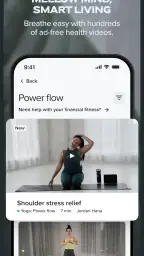
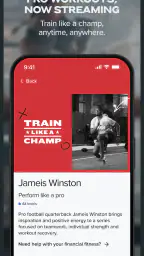
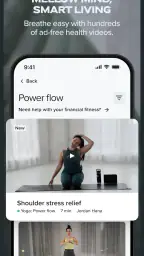
- Wellness Tips: This was a pleasant surprise. The app includes a section dedicated to mental and physical wellness, offering tips to help you manage stress and stay healthy — because financial health is just one piece of the puzzle.
- Home Management: If you’re a homeowner, you'll love this feature. It helps you keep track of home maintenance tasks, from paying utility bills to scheduling repairs.
Getting the Most Out of It
Using the app to its full potential means spending a bit of time setting up your preferences and inputting your data. Trust me, it's worth it. Once you’ve got everything in place, the app really starts working for you. Every time you make a purchase, you can log it, and the app updates your budget in real-time. The notifications are also a lifesaver, reminding you of upcoming bills and tasks you need to tackle.
One thing I've found particularly useful is the goal-setting feature. You can set financial goals, like saving for a vacation or paying off a credit card, and the app will help you track your progress. It’s incredibly motivating to see your savings grow, and it adds a fun element to the sometimes tedious task of budgeting.
What to consider before making it a household habit
Although I like the idea of keeping financial planning and home responsibilities close together, the app will not suit everyone equally. If you want a dedicated investment tracker, tax organizer, or automatic bank-account dashboard, I would look for a tool built specifically around that need. If your main concern is simply remembering when rent is due, a calendar may take less effort. This app makes the most sense when you actually want to engage with more than one part of household wellbeing.
Another trade-off is the effort of keeping a budget current. Logging purchases and entering information can be useful precisely because it makes you notice patterns, but it asks for consistency. If you stop recording transactions, the budget can become stale and the insights less helpful. I would begin with a manageable level of detail instead of trying to categorize every small purchase from day one. A routine you can maintain is more valuable than a meticulous setup you abandon.
For a first run, I would choose one clear goal and one home responsibility to track. That gives you a way to judge whether the app’s mix works for you without turning setup into a major project. After a few check-ins, ask whether the information changed a decision: Did it help you notice a spending category to review, remember a task, or make a savings plan feel more concrete? If not, simplify the routine or use a more focused alternative.
One question people often have is whether it can serve as the household’s only financial record. I would not treat it that way. Use the relevant bank or bill provider to confirm balances, payments, and due dates, and treat the app as a place to organize and reflect on the plan. Another natural question is whether everyone in a home needs to use it. In my view, no: a household can benefit from one person maintaining a plan, as long as the others know what is being tracked and agree on how decisions are made.
People also wonder whether its wellness material makes it a health app. I see that content as a complement to its financial and home focus, not a reason to rely on it for medical advice or personal care. Likewise, a goal tracker can help make a plan visible, but it cannot guarantee that a saving target is realistic; income, essential bills, and unexpected costs still matter. I would use the app to support practical decisions, not to outsource them.
Final Thoughts
After spending some quality time with the app, I can confidently say that it's a game-changer for anyone looking to take control of their finances while maintaining a balanced lifestyle. It’s not just about dollars and cents; it’s about fostering a healthier relationship with your money.
For a household, I would recommend it most to someone who wants a gentle structure for budgeting, personal goals, and home tasks, and who is comfortable entering information and keeping it current. I would skip it if you need a fully shared account system, a specialist tool for splitting expenses, or a passive service that handles every update for you. Its strongest role is as a planning companion that can help turn vague intentions into a routine, provided the people involved agree on privacy and responsibilities.
The app is available for both Android and iOS, and you can download it directly from the Google Play Store or the Apple App Store. If you’re ready to take the plunge into financial wellbeing, this app is a must-try. So go ahead, give it a whirl, and let me know what you think!
Frequently Asked Questions
What is the main purpose of the Rate: Home, Finance & Wellness app?
Rate: Home, Finance & Wellness is designed to help users manage their financial health by providing tools for budgeting, expense tracking, and financial goal setting. It also offers personalized insights and recommendations to improve overall wellness, making it a comprehensive solution for both personal finance and well-being.
Is Rate: Home, Finance & Wellness free to use?
The app offers a free version with essential features for budgeting and expense tracking. However, it also has a premium subscription that unlocks additional tools such as personalized financial insights, advanced analytics, and wellness tips. Users can choose the plan that best fits their needs.
How does Rate: Home, Finance & Wellness ensure data security?
Rate: Home, Finance & Wellness prioritizes user privacy and data security by employing industry-standard encryption methods. User data is stored securely, and the app regularly updates its security protocols. Additionally, users have control over their data with options to manage privacy settings and permissions.
Can Rate: Home, Finance & Wellness sync with my bank accounts?
Yes, the app allows users to securely link their bank accounts to automatically track transactions and update budgets in real-time. This feature helps users maintain an accurate overview of their financial situation without manual data entry, ensuring a seamless and efficient experience.
What kind of wellness features does the app offer?
Beyond financial management, Rate: Home, Finance & Wellness provides wellness features such as stress management tips, mindfulness exercises, and goal-setting tools to enhance mental and emotional well-being. These features are designed to complement financial health, promoting a balanced and healthier lifestyle.


